Eagle Pro Roofing Resource Center | Houston, Pearland and Sugar Land
A Texas roof claim begins with a policy, a covered event and a damage assessment—not a roofer promising a free replacement. Understanding deductibles, depreciation and what contractors can legally do will help homeowners make better decisions following severe weather.
What homeowners should know
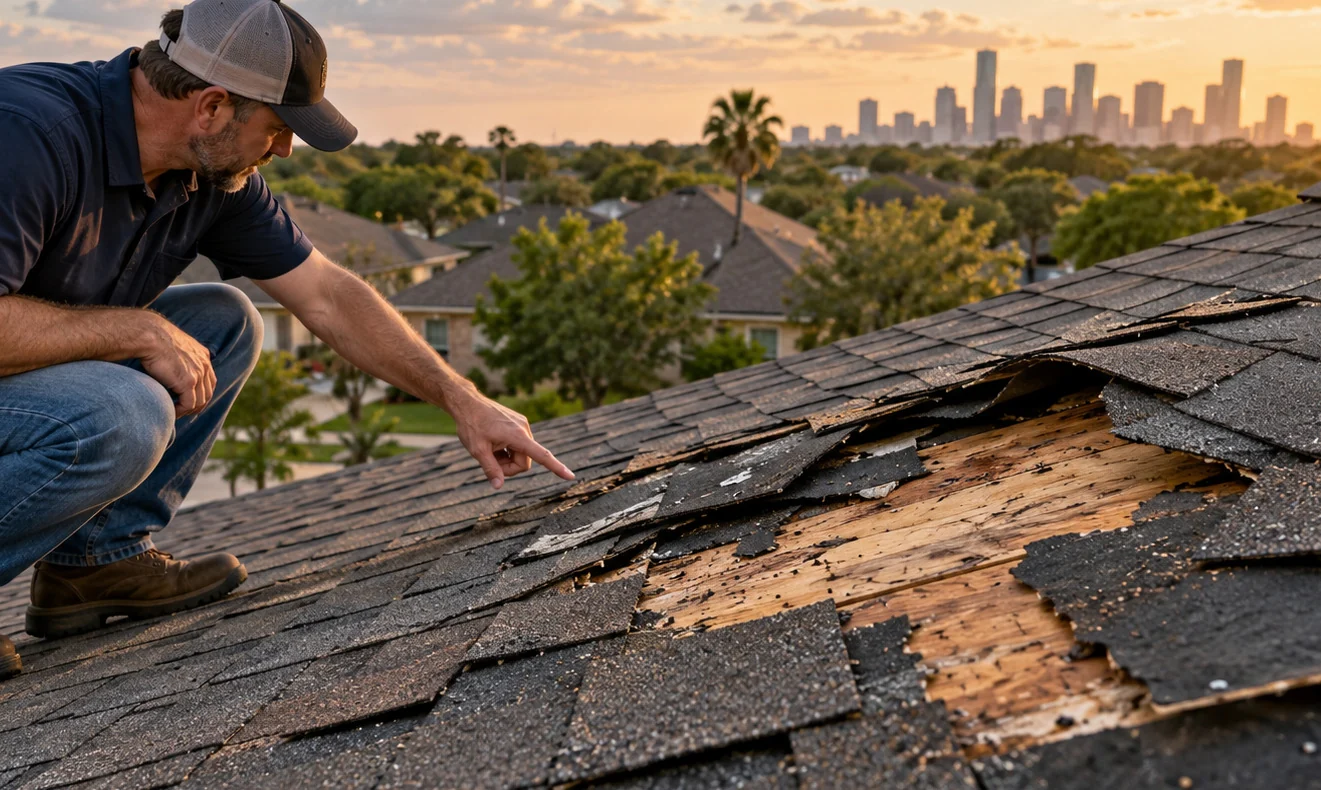
1. Storm damage does not automatically mean replacement
Insurance coverage depends on cause of loss, policy wording, exclusions, inspection findings and whether repair is appropriate.
What to ask: “Can you show me exactly where this appears in my written proposal?” A careful explanation should distinguish work included in the base price from potential extra work.
2. Percentage deductibles add up
A 2% wind/hail deductible on a $400,000 insured dwelling value would be $8,000, if that is the applicable base under the policy.
What to verify: Ask for photographs or a sample specification. Write down the answer while comparing contractors; memory is unreliable when estimates use different terminology.
3. Texas prohibits deductible waivers
A roofing contractor cannot legally rebate, waive or absorb the insured’s deductible on a covered project.
Why it matters in Greater Houston: Heat, humidity, heavy downpours and periodic high winds make the details of water management and installation worth discussing—not simply the appearance of the finished shingles.
A useful follow-up question: “Will this be shown on my written estimate or inspection report, and can you explain what happens if the conditions differ once the work begins?”
4. Roofer and public adjuster are different roles
A contractor may estimate repairs and document damage but cannot lawfully act as a public adjuster on the same project.
Before agreeing: Request a written confirmation of the method or product and learn who makes the final decision if the crew discovers different conditions during the job.
5. Actual cash value and replacement cost differ
Depreciation and policy terms can change when and how much the insurer pays.
How to compare alternatives: Have competing roofers explain their different approaches in plain language. A more expensive choice is worthwhile only when the added scope or performance is clear.
Practical next steps
Document damage safely, limit additional harm, contact your insurer and request an itemized roofing assessment.
Insider takeaway: Quality depends on good diagnosis, suitable materials, correct installation and a process for resolving problems. No single product claim proves all four.
A useful follow-up question: “Will this be shown on my written estimate or inspection report, and can you explain what happens if the conditions differ once the work begins?”
Questions to take to your appointment
- What exact roof conditions did you observe, and can I see the photographs?
- Which repair or replacement options are reasonable, and why?
- What materials, labor, cleanup and protective measures are included in this price?
- Who supervises the work and how are changes approved?
- What installation instructions, warranty terms and permit requirements apply to this property?
Frequently asked questions
Does this advice apply outside Houston?
Yes. Homeowners in Houston, Pearland and Sugar Land can use the same comparison method, but jurisdictional permitting, product suitability and roof design can vary by address. Confirm the requirements for the actual property.
Should I choose the lowest roofing quote?
Not based on the total alone. First compare materials, tear-off, flashing, underlayment, ventilation, decking allowances, warranties and cleanup. A lower quote may still be good value if the work is comparable.
Can a contractor tell me what insurance will cover?
A roofer can document observed conditions, prepare repair estimates and discuss technical details. Your insurer determines coverage under your policy. Texas prohibits a contractor from acting as a public adjuster on a project the contractor provides or may provide work on.
The bottom line
The insurance company decides coverage under the policy, and the contractor estimates construction. Keeping those roles separate protects the homeowner.
Request a roofing consultation in Greater Houston
If you are evaluating a roof repair or replacement, contact Eagle Pro and request a written assessment and clear scope of work. Bring these questions and ask for practical explanations of the options for your home.
References and further reading
- Texas Department of Insurance — Roofing and insurance: Know the law
- Roofing Contractors Association of Texas — Consumer guide
- Texas Department of Insurance — Insurance deductible guidance
Educational information, not an individualized roofing inspection, legal opinion or guarantee of insurance coverage. Confirm permit rules with the authority having jurisdiction and system details with the manufacturer.